Texas Manufactured Housing Market Report - Sales Data & Analysis
Rob Ripperda
September
First Read
September is only about 46% titled at this point, but we can use installation reports to fill the gap. Installers’ Form-T filings reach TDHCA within days of the install, and a home’s installation tends to land a few days before its recorded transfer of ownership date.
Blending September’s titles issued to date with its installation reports points at roughly 1,290 new home sales (± 120) for the month.
The plot below shows how this method has scored so far. Installations ran well ahead of titles in June and July, as they did a year earlier, so the summer misses on the plot may be a seasonal pattern the blended model can’t account for until a second year confirms it.
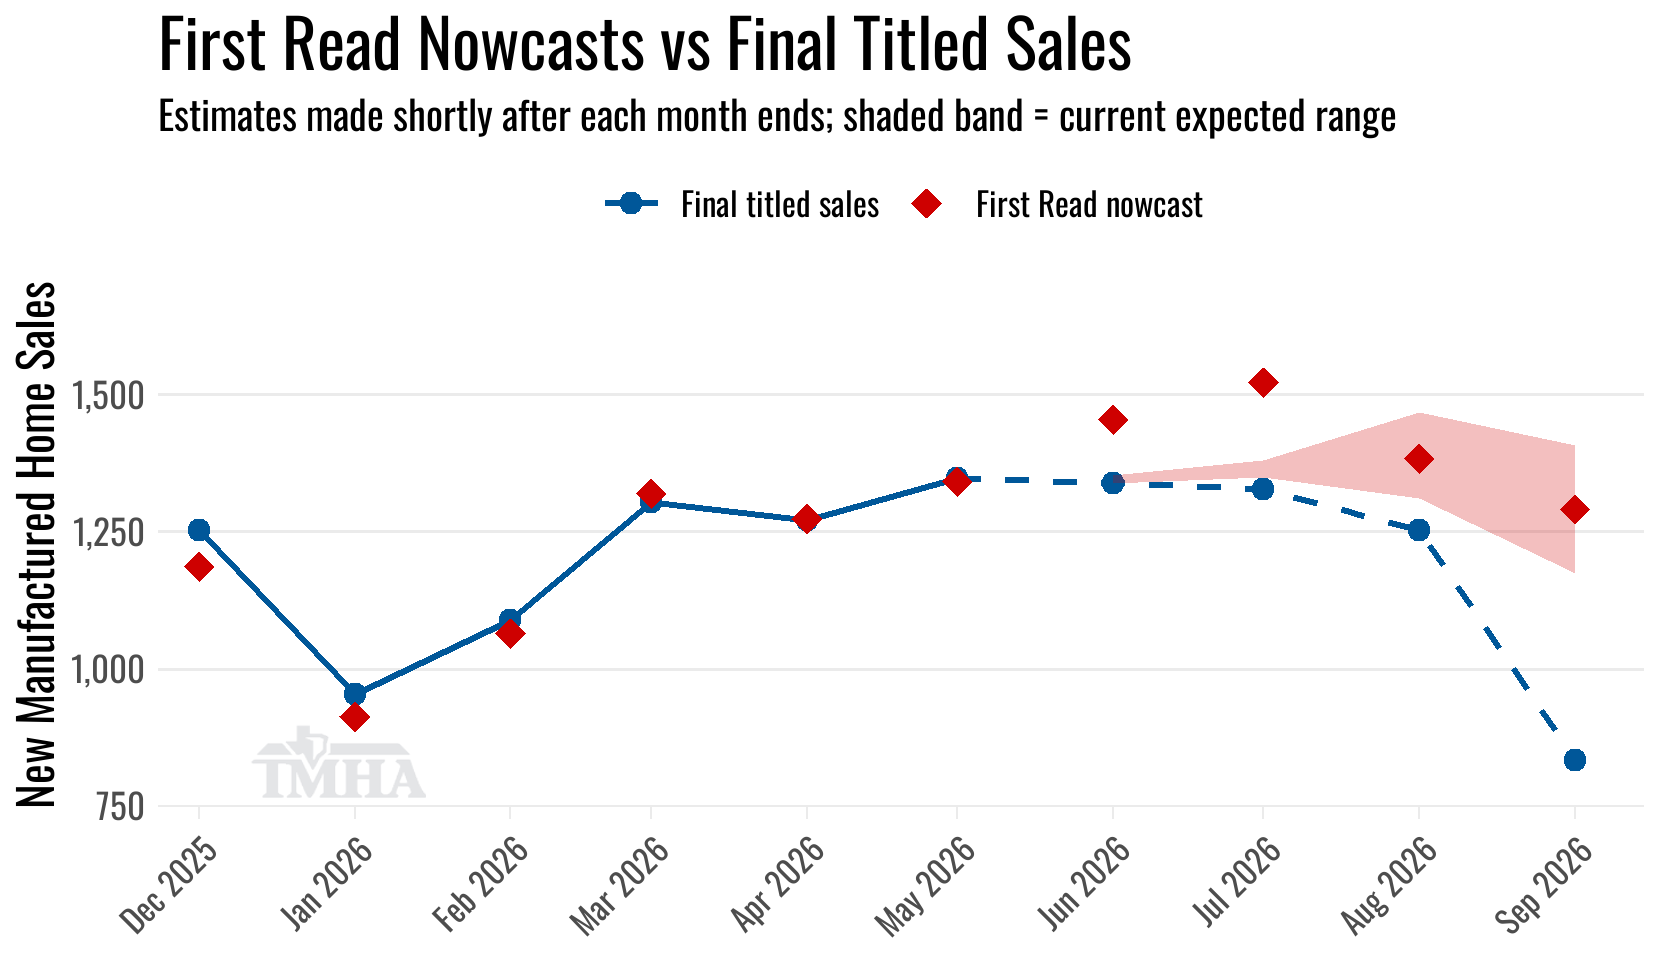
Note: Every diamond is the model’s First Read for that month. Months on the solid line are old enough for their totals to be effectively final. For the months still accumulating titles, the dashed line traces the titles actually issued so far and the shaded band shows the range where each is currently expected to settle, incorporating everything reported since its First Read.
August
Early Look
New manufactured home sales for August 2026 titled to date are so far down a seasonally-adjusted 4.1% from the previous month and are running 4.8% below August of 2025. August of 2025 settled at 1,479 homes, the largest month of last year’s second half, so this is the toughest year-over-year comparison in the cycle, and the cadence inflation that flattered the spring and early summer readings is now out of the comparison.
About 90% of a sale month’s eventual total is already on the books at this point in the reporting cycle. That puts August on pace to settle near 1,390 new home sales (± 80) once the remaining titles are issued. That would land within about 6.1% of August of 2025’s final total of 1,479, with the top of the expected range falling just short of last year’s figure.
As the plot below shows, August’s early count is running just below last year’s line at the same point now that last year’s faster titling sits in the comparison months.
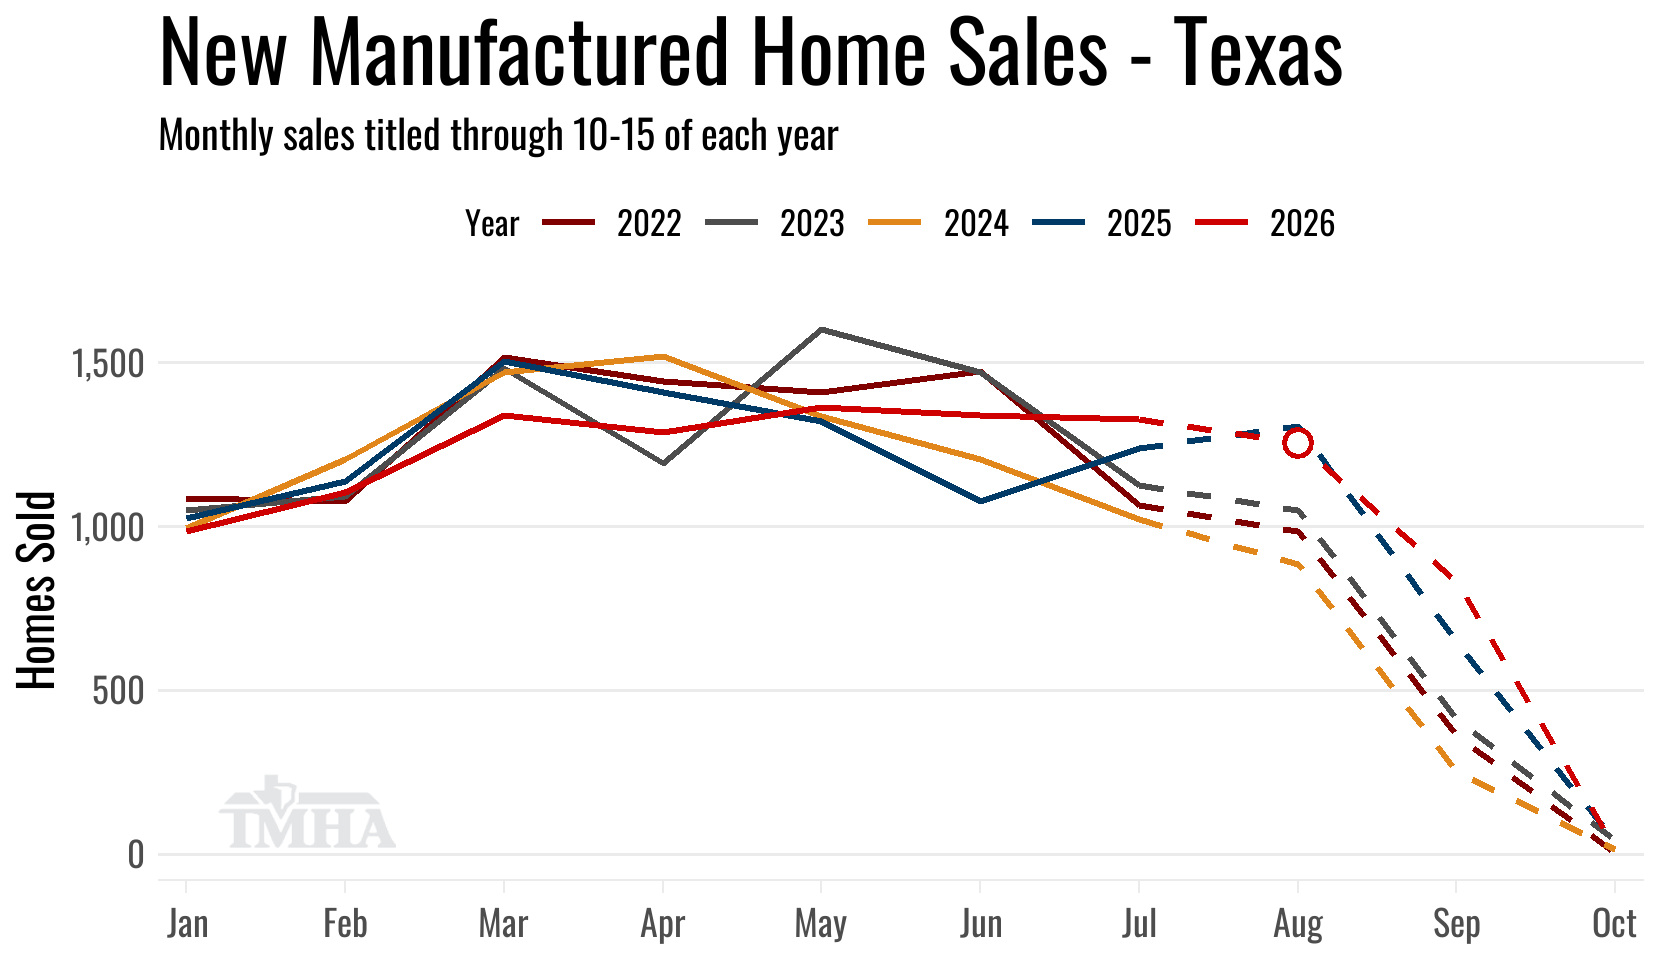
Solid lines represent months for which the on-time titling window has closed. Dashed lines are preliminary months for which titles are still being counted toward the reported total.
The comparisons in the table below are based on where the previous month’s numbers were when originally reported on one month ago.
| New Sales | Singles | Multis | Total |
|---|---|---|---|
| Total for August: | 446 | 806 | 1,252 |
| Change from July (Raw %): | 7% | -0.1% | 2.3% |
| Change from July (Raw Units): | 29 | -1 | 28 |
| Change from July (SA %): | 2.7% | -3.9% | -4.1% |
| Change from August of 2025 (%): | -3% | -5.7% | -4.8% |
| Change from August of 2025 (Units): | -14 | -49 | -63 |
TMHA Member’s Retailer Annual Sales Totals Report
July
Titled on Time
New home sales for July titled to date were up a seasonally adjusted 5.9% from the previous month and are up 7.2% on the raw total from July of 2025.
July’s 1,327 homes sold edged past June and May, the third straight on-time report month above 1,300 and the best of the three. Multi-section sales carried it, up 18% from July 2025, while single-section sales fell 9%.
With July roughly 97% complete at publication, expect the month to settle near 1,360 new home sales (± 20) as the last titles are issued.
That settled estimate would land about 2% above July 2025’s final total of 1,338. July of 2025 was the first month after the change in title timing took hold, so this is the first on-time comparison that is close to apples to apples, and it still shows a modest gain. From here the comparisons run against the second half of 2025, when faster titling was already in place.
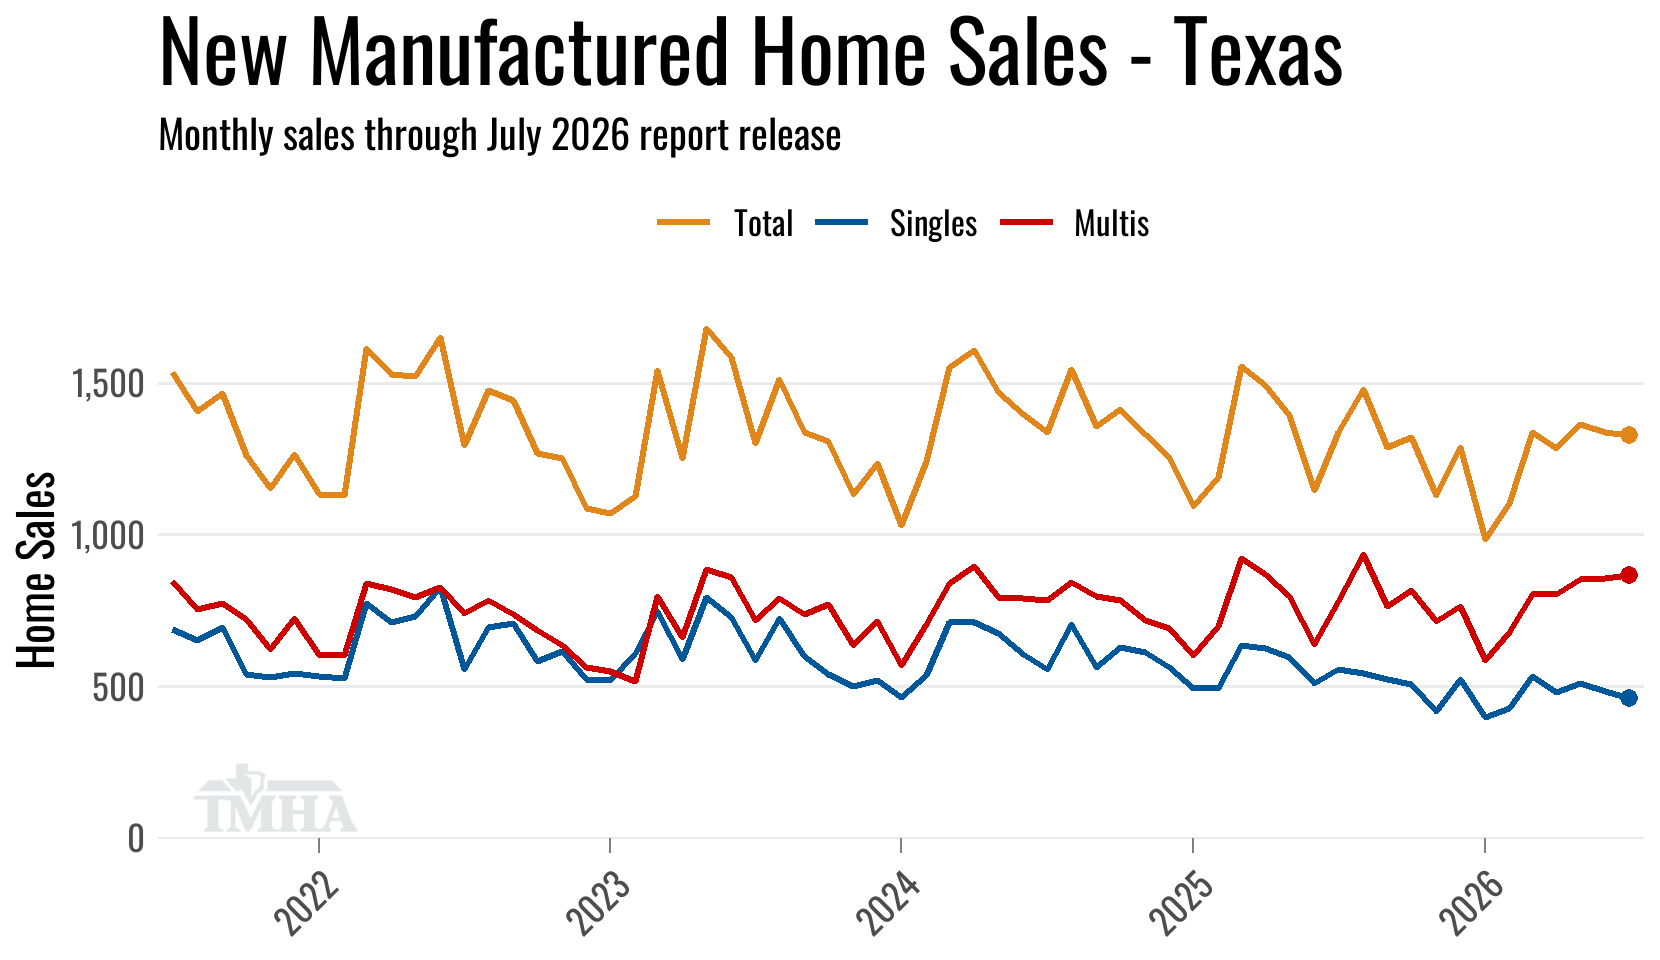
While the plot above contains revised totals for previous months the comparisons in the table below are based on where the previous month’s numbers were when released one month ago.
| New Sales | Singles | Multis | Total |
|---|---|---|---|
| Total for July: | 461 | 866 | 1,327 |
| Change from June (Raw %): | -2.1% | 3.2% | 1.3% |
| Change from June (Raw Units): | -10 | 27 | 17 |
| Change from June (SA %): | 1.9% | 7.2% | 5.9% |
| Change from July of 2025 (%): | -8.7% | 18.1% | 7.2% |
| Change from July of 2025 (Units): | -44 | 133 | 89 |
TMHA Member’s Retailer Monthly Sales Totals Report
Titled Installation Location Trends
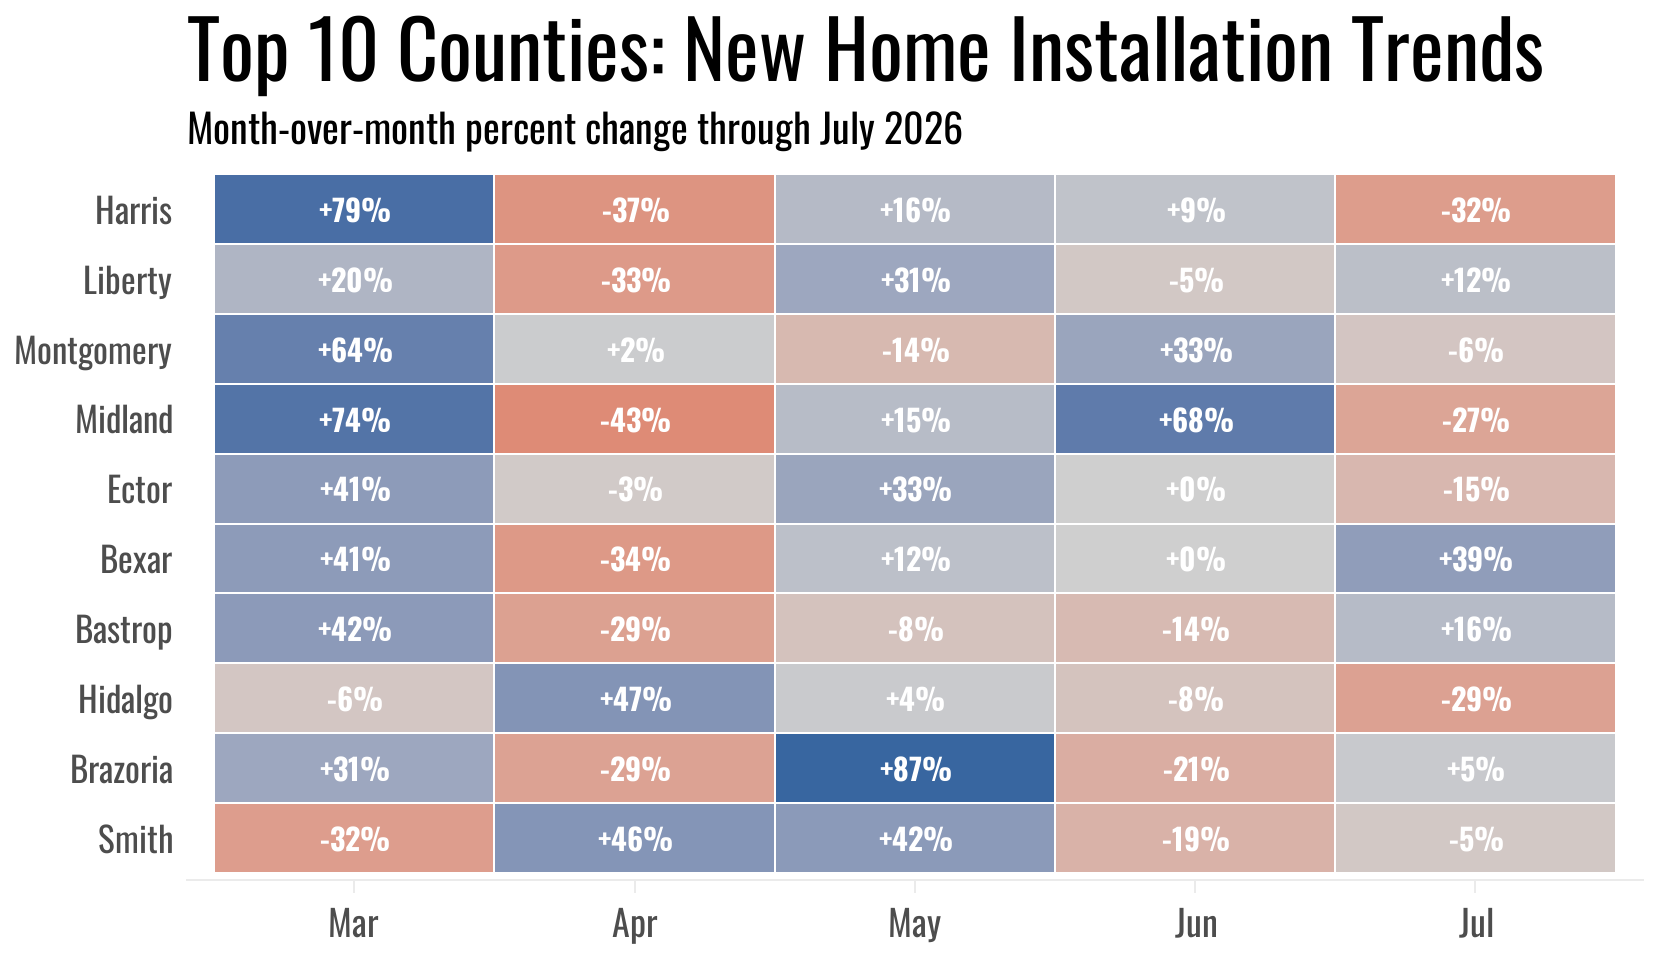
Here are the month-over-month changes for the top 10 counties for new home sales over the past five on-time report months, ranked by their total placements across that span.
July turned the table over. Bexar jumped 39%, its best month in the window, Bastrop rose 16%, Liberty 13%, reaching 45 homes to tie Montgomery for the top spot, and Brazoria 5%. The other six slipped: Harris fell 32%, to 32 homes, its lowest month in the window, Hidalgo dropped 29%, Midland gave back most of June’s surge (down 27%), and Ector (15%), Montgomery (6%) and Smith (5%) eased.
TMHA Member’s Retailer Annual Sales Total per County Report
Annual Totals
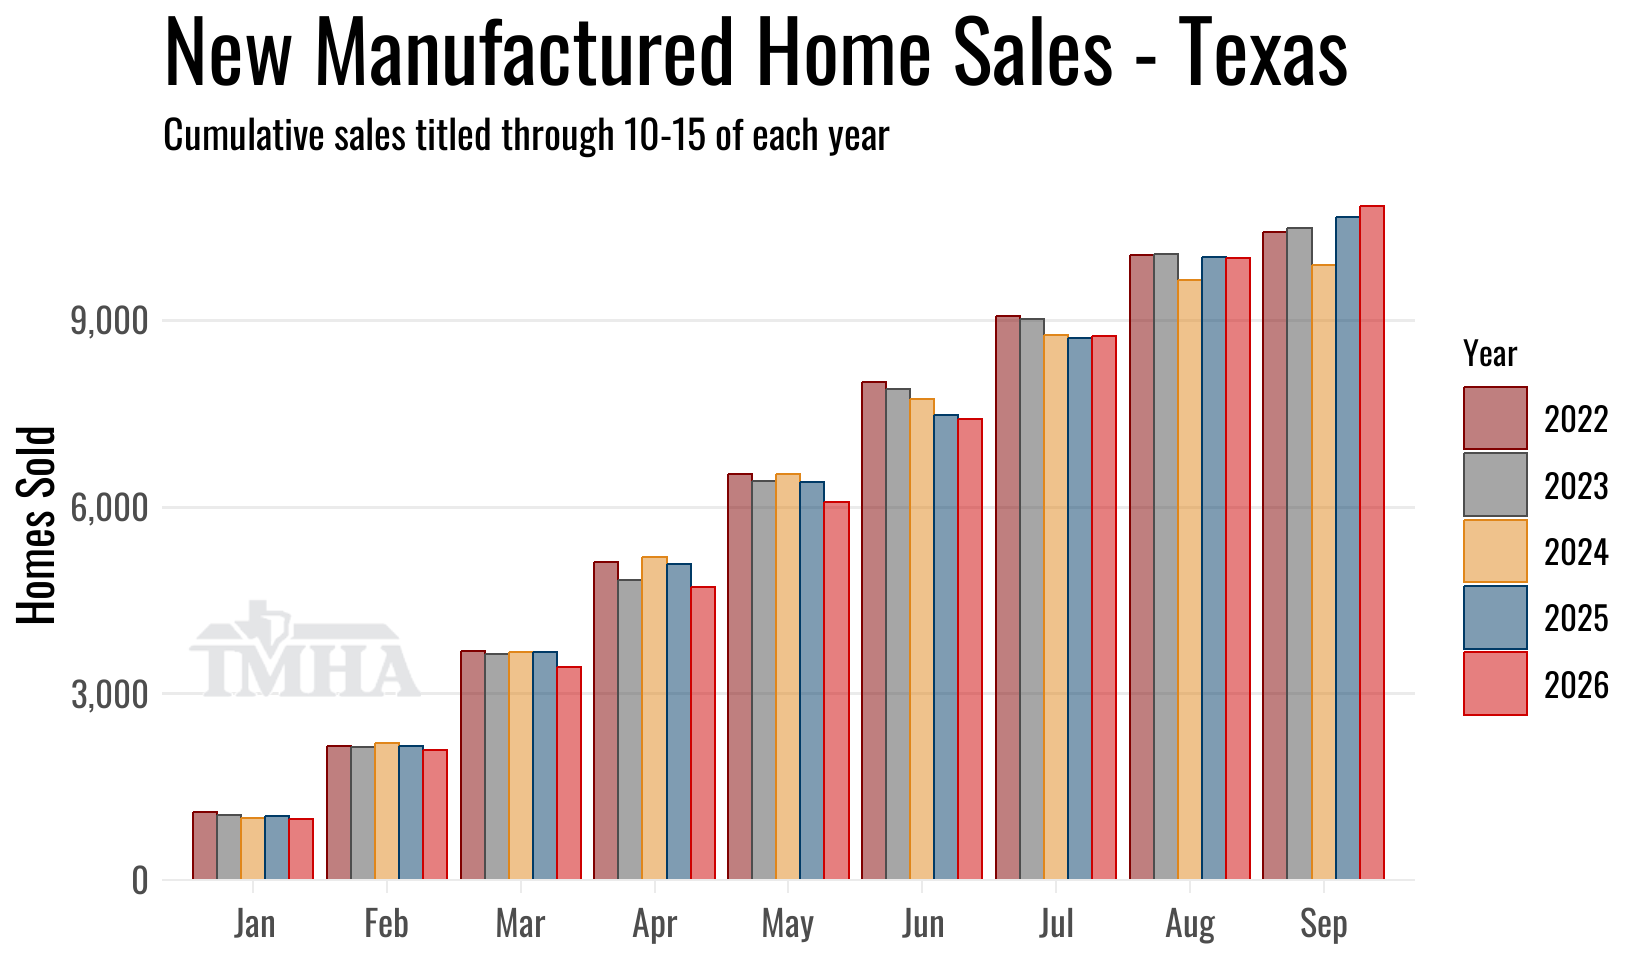
New home sales in 2026 are showing a 1.4% gain year-over-year for titles processed through this point compared to 2025.
Multi-section sales are up 7.7% year-over-year while single-section sales are down 7.8%.
As noted above, the titling phase shift inflated 2026’s year-over-year comparisons through the first half of the year, some of it simply pulling sales into June and July that a year ago would have been tallied as revisions to earlier months. With July and August now compared against post-change months, the annual lead is a slim one and should keep compressing through the fall as the cadence effect washes out of the cumulative total.
We can also look at the statewide installation reports, which are running about 4% below last year’s pace year-to-date. That is a useful check on 2026’s narrow lead over last year: it’s faster titling, not a surge of homes going into the ground.
| New Sales | Singles | Multis | Total |
|---|---|---|---|
| Total for 2026 titled to date: | 4,032 | 6,809 | 10,841 |
| Change from 2025 (%): | -7.8% | 7.7% | 1.4% |
| Change from 2025 (Units): | -343 | 488 | 145 |
TMHA Member’s Retailer Annual Sales Totals Report
New Home Characteristics
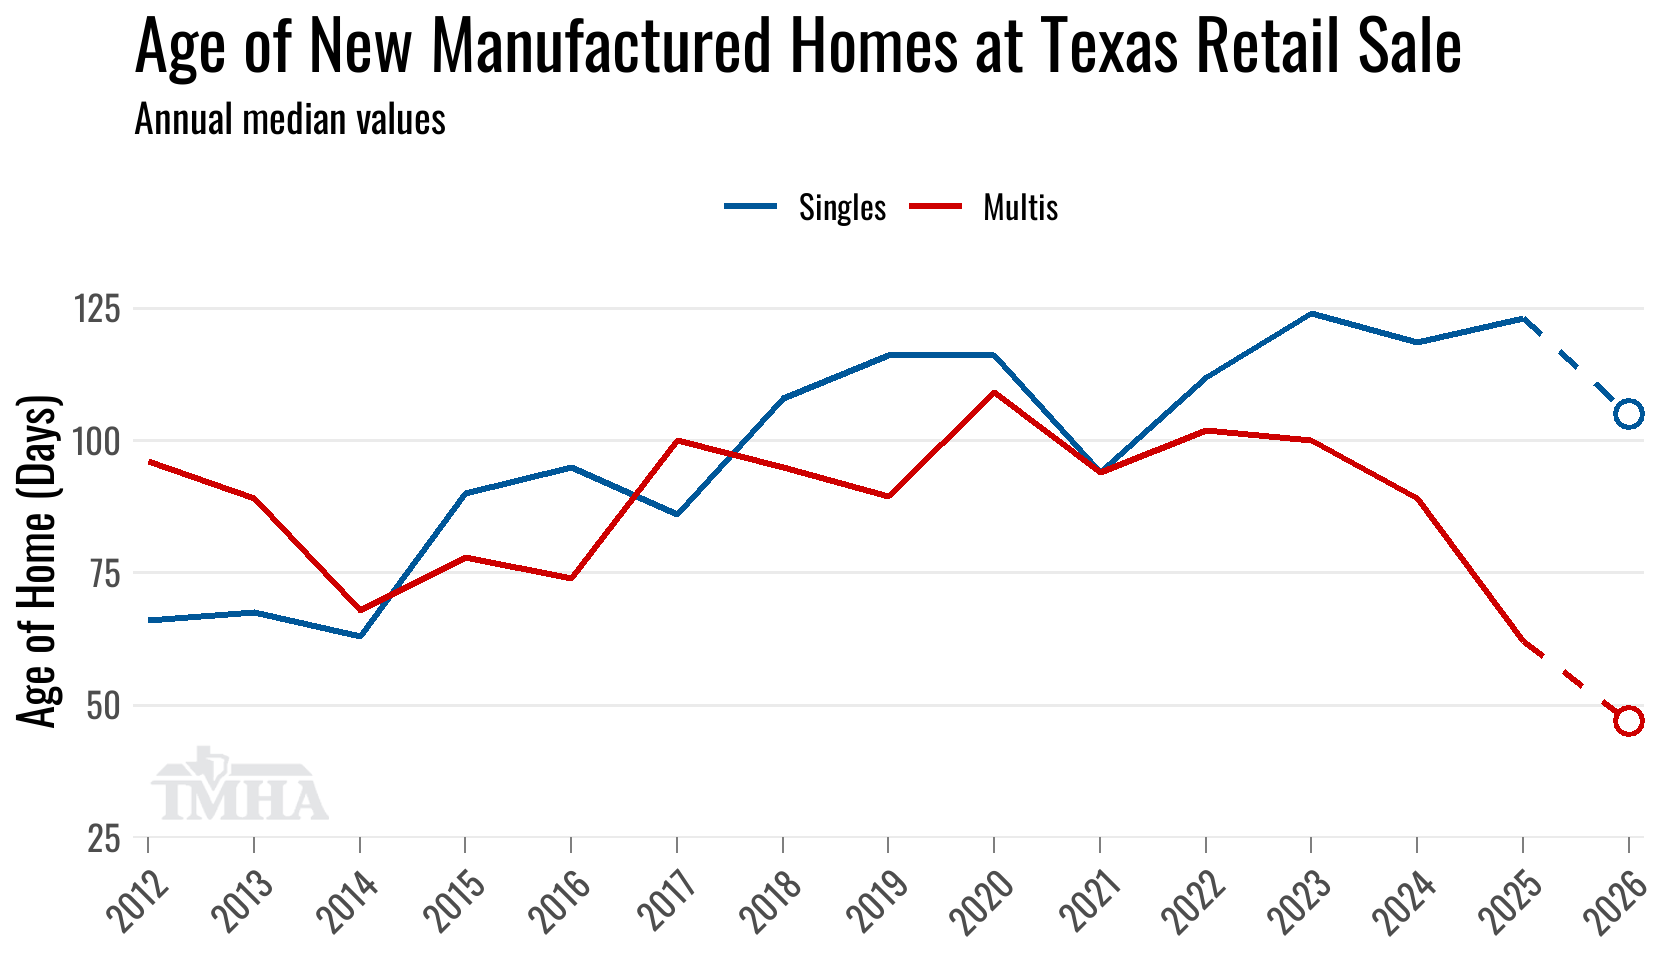
The shift in title cadence has really pulled down the median age of multi-section homes to the shortest amount of days in our records, and single-section homes are following, if less smoothly. July’s single-section median came in at 107 days, up from June’s low for the year but still well below the 120-plus days that prevailed through 2025, while multi-section homes held at 46 days. Year to date the medians stand at 105 days for singles and 47 for multis, which says single-section inventory genuinely is turning faster, even if the month-to-month path is noisy. Given how much the median has moved for multi-section homes, we suspect the change in date of sale guidance had an outsized effect on those home sale transactions, but the single-section market has also underperformed the multi-section market for several years now, so it makes sense those homes had been taking longer to turn.
| New Home Characteristics for 2026 | Singles | Multis | Total |
|---|---|---|---|
| Median Age of Home (Days): | 105 | 47 | 64 |
| Median Square Footage: | 1,080 | 1,699 | 1,475 |
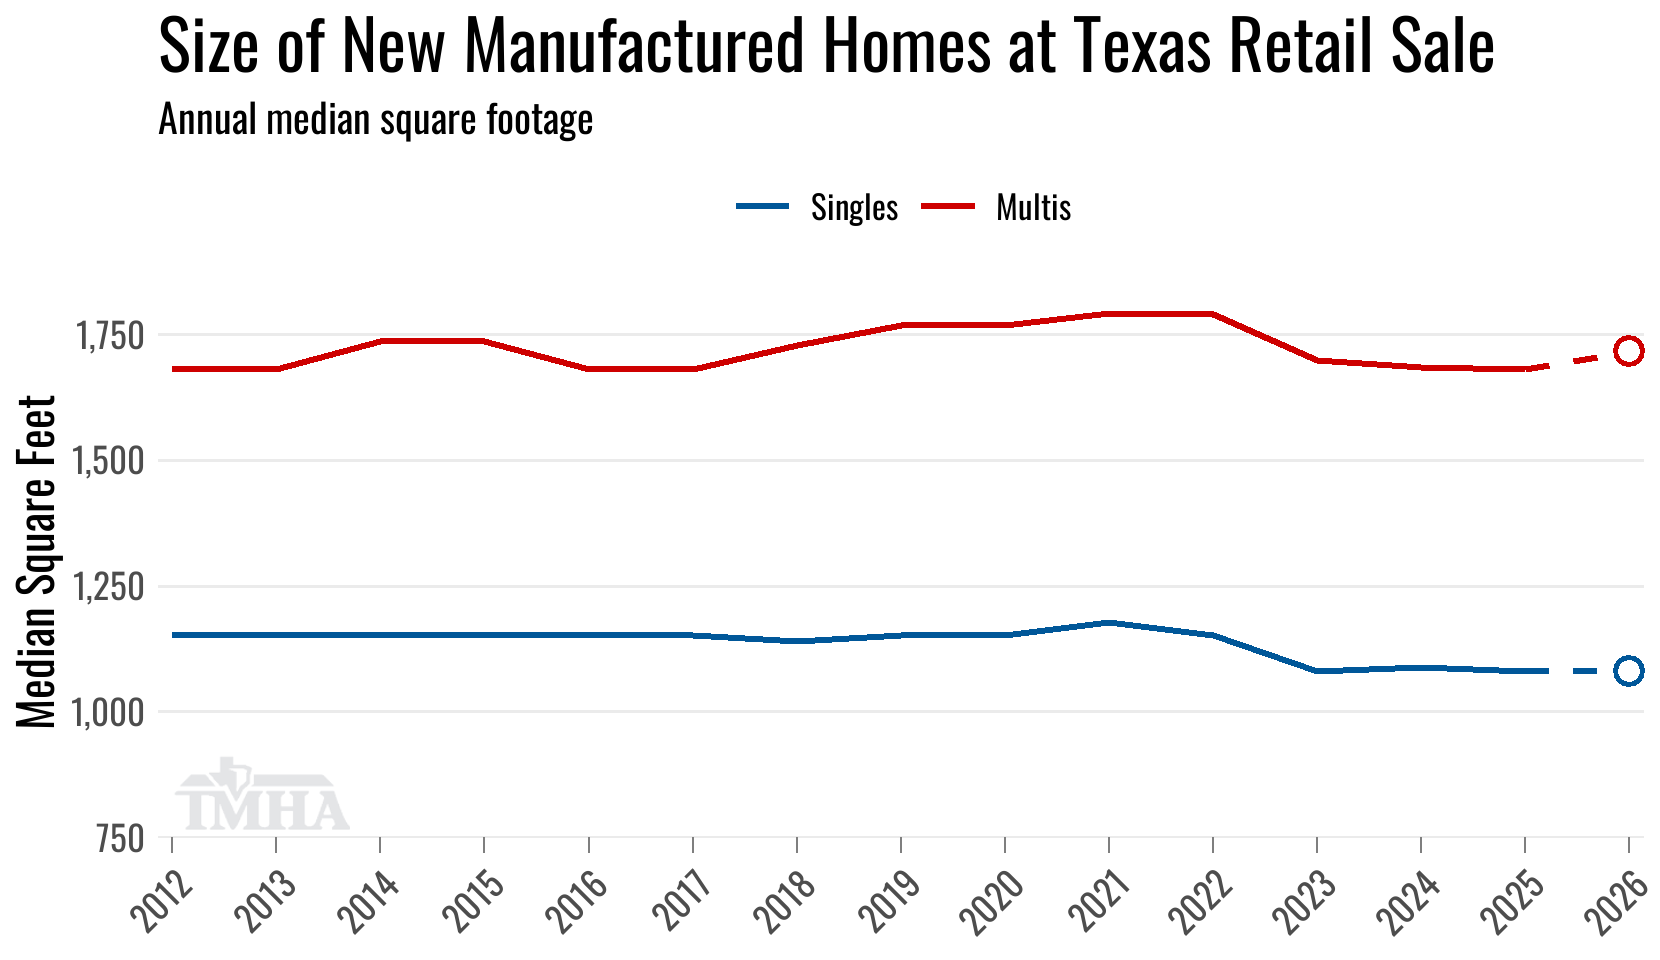
Beyond the age of homes at purchase, the square footage plot below shows a structural shift in Texans downsizing new home purchases when the affordability squeeze set in. The break is sharp and lands in a single year: both section types held their long-run size through 2022 and stepped down together in 2023. Multi-section medians moved from roughly 1,790 square feet to about 1,700, and single-section homes from roughly 1,150 to 1,080, where both have held since. Multis are running 1,699 so far this year, a modest uptick, though 2026 is a partial year and still settling.
New Home Placement Locations
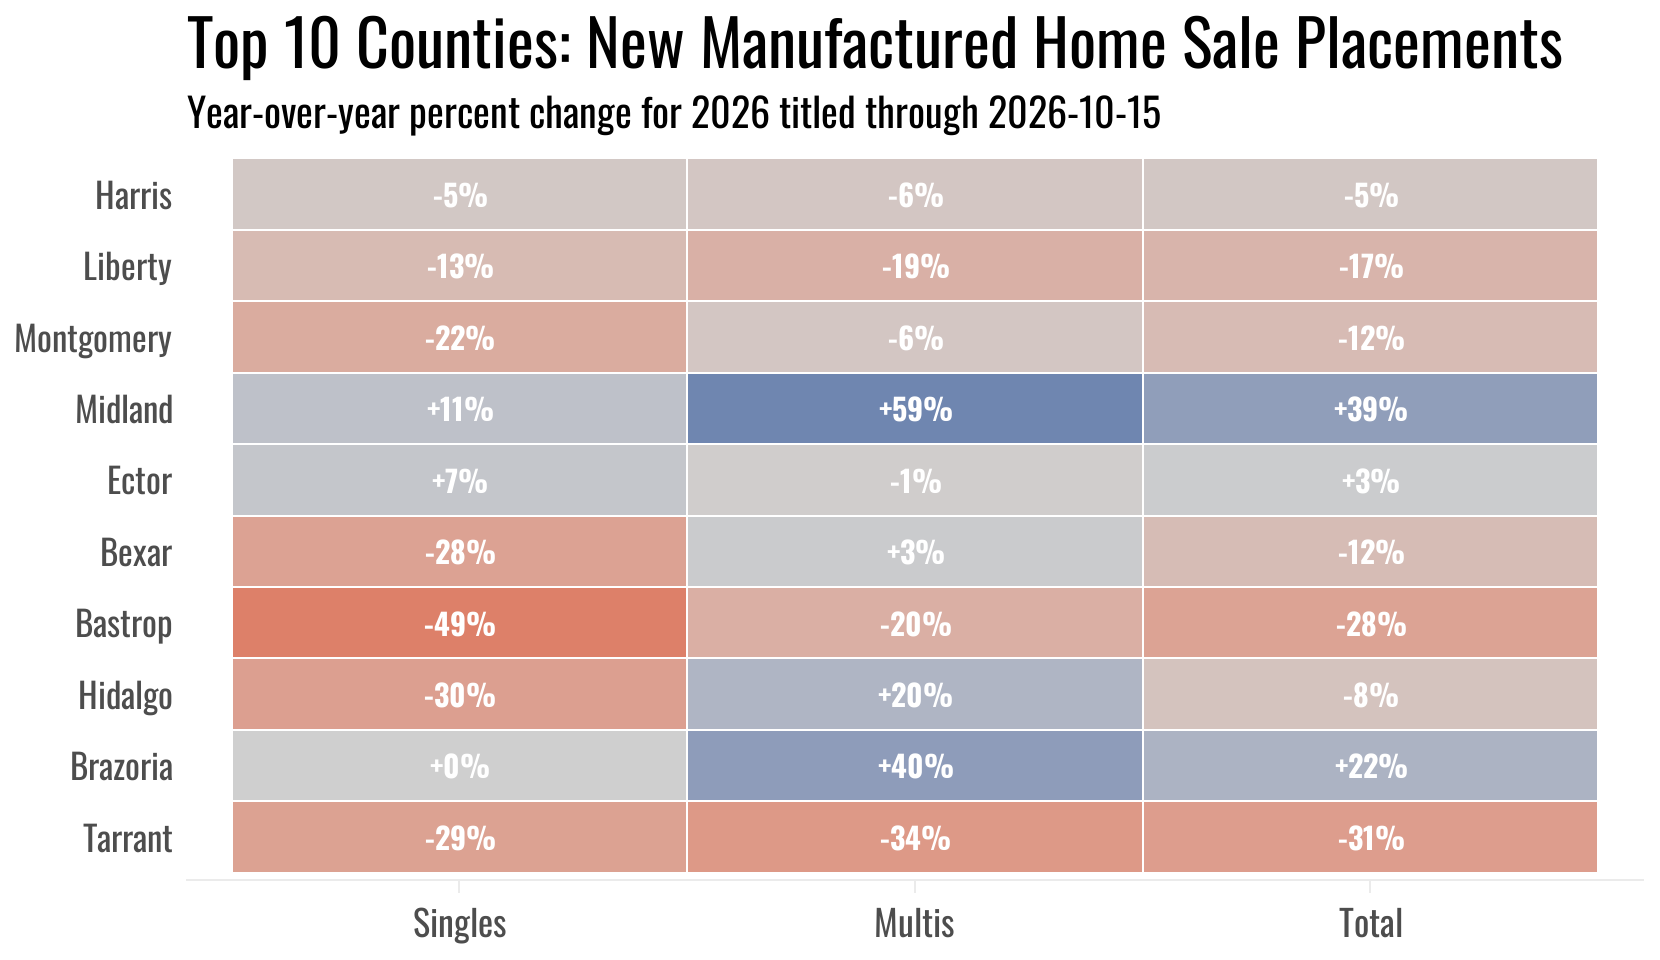
Here are the breakdowns in year-over-year changes for the top 10 counties in new home placements across home section types.
Midland, fourth in volume, leads the top 10 in year-over-year growth at +39.0%, well clear of Brazoria at +22.0%; Ector (+2.5%) is the only other county ahead of last year’s pace through October 15. The remaining seven are behind, with Tarrant down 31.4%, Bastrop down 27.8% and Liberty down 16.9% showing the steepest declines, and Harris, the volume leader, off 4.9%.
TMHA Member’s Total Annual Retail Sales per County Report
Shipment Comparison
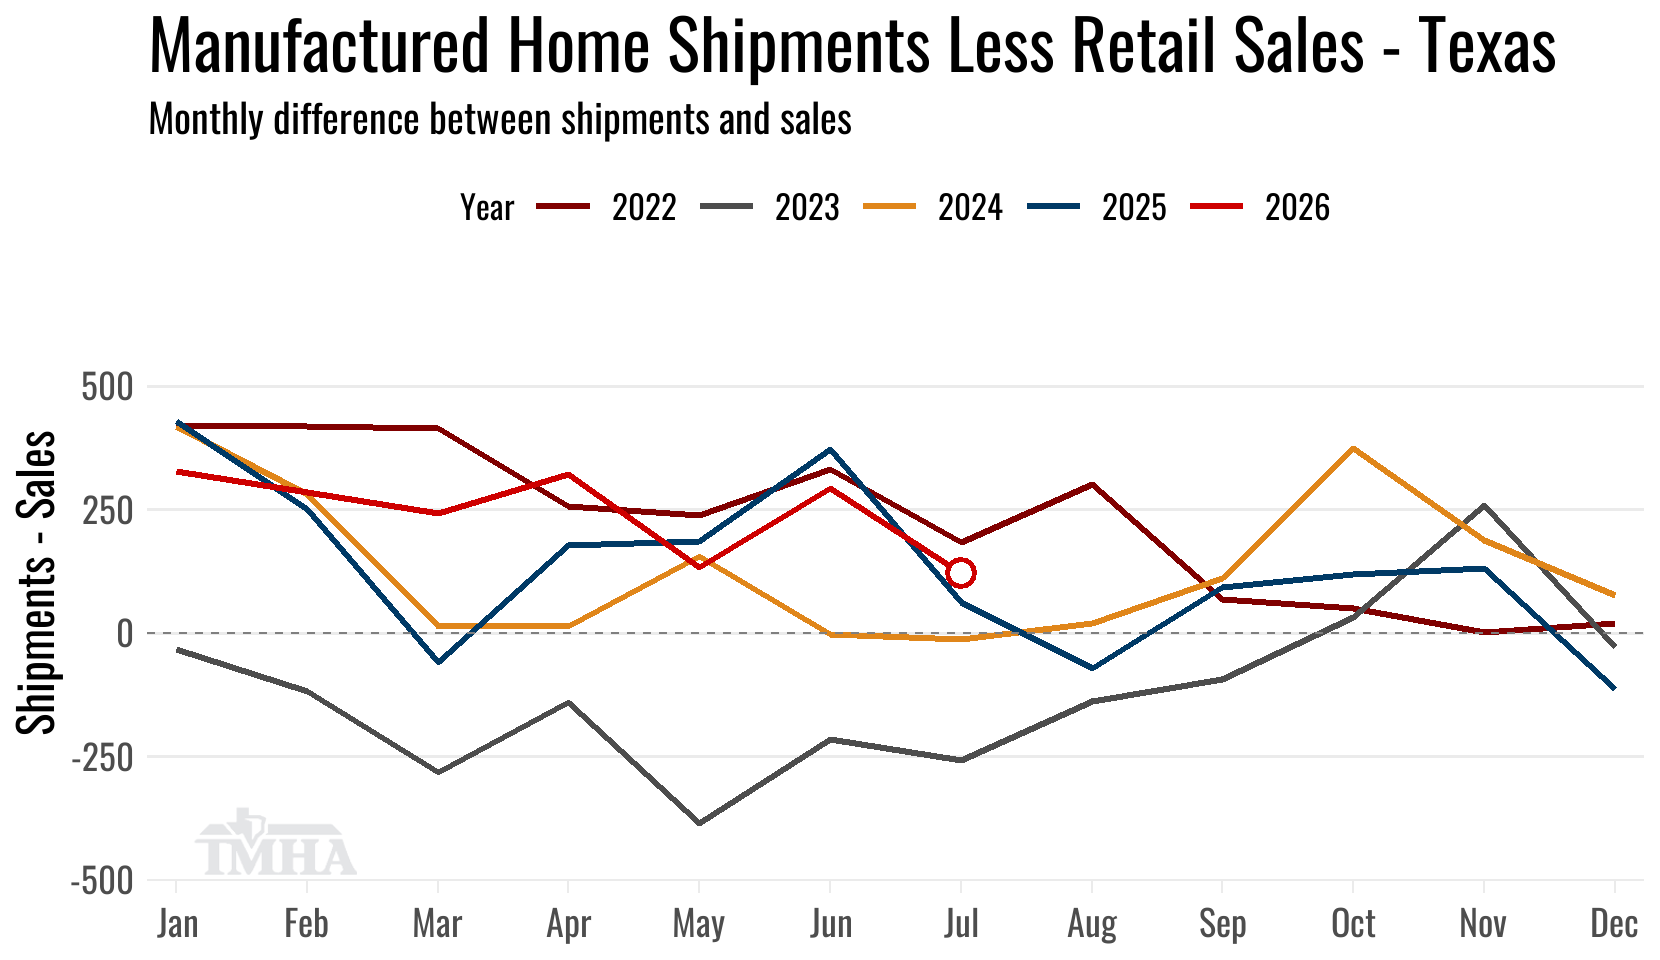
The gap between shipments and titled retail sales narrowed in July. June’s difference settled at 293 homes once its late titles arrived, but July’s 1,448 shipments ran only 121 ahead of the 1,327 new home sales titled for the month, and with July nearly complete that should close to roughly 85, not far from the 62-home gap of July 2025. August’s early look points the same way: 1,425 shipments against 1,252 sales titled to date leaves a 173-home difference that should shrink to a few dozen as August’s remaining titles arrive.
Moving Averages
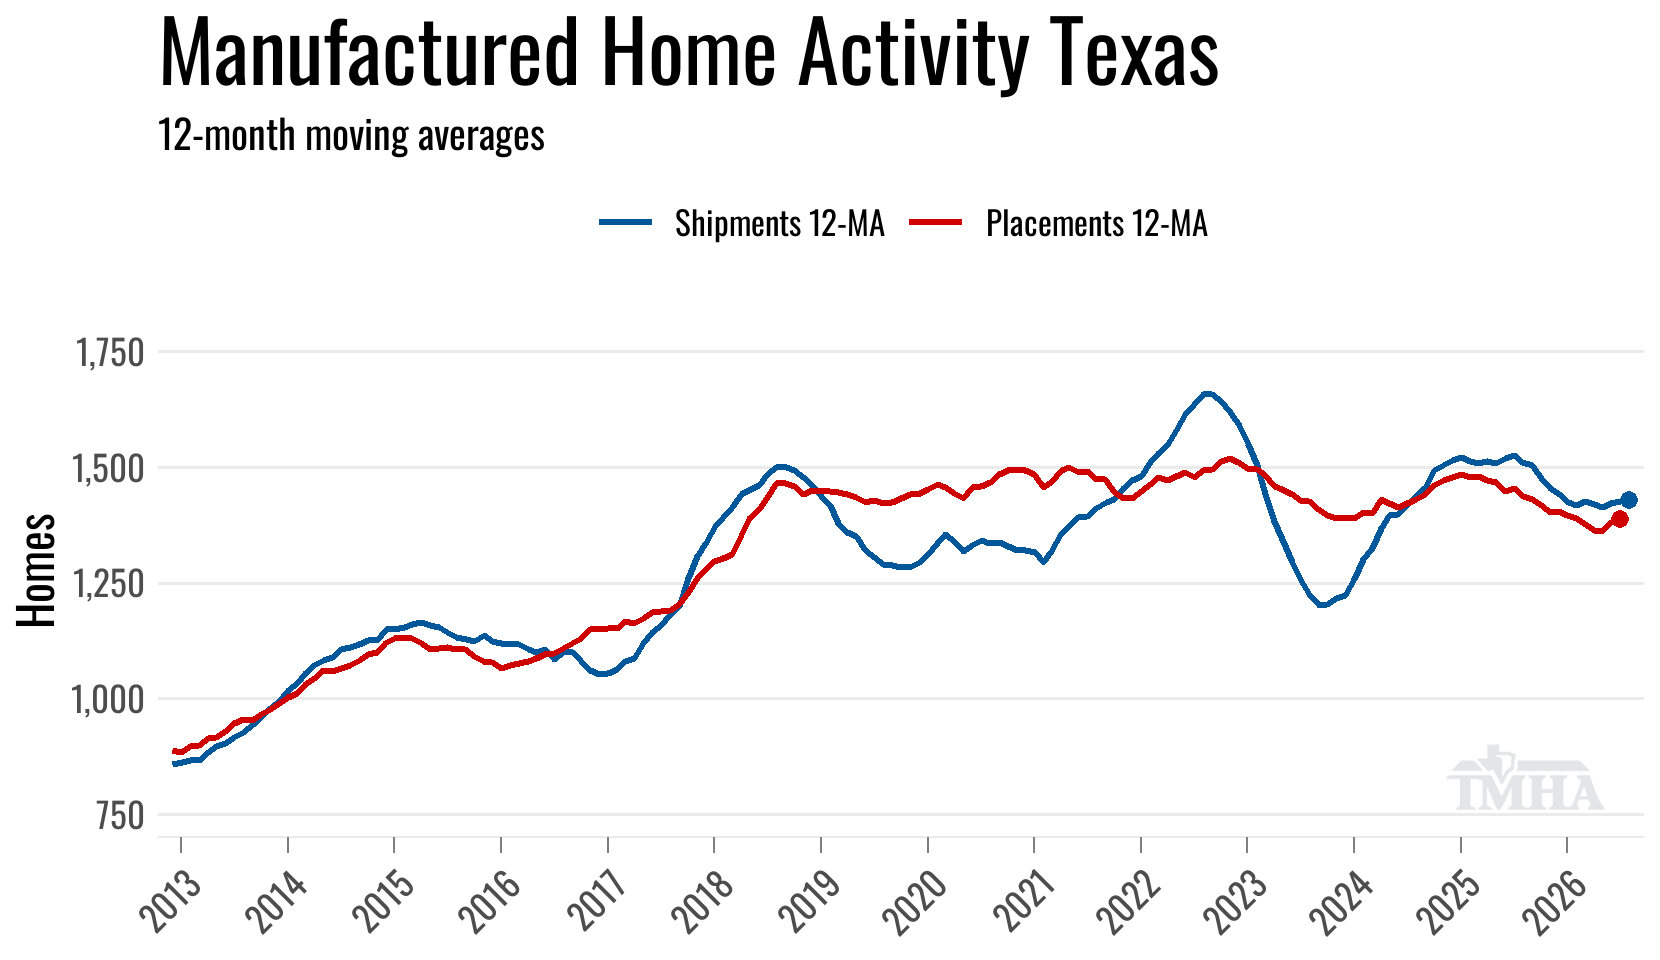
The plot below compares the 12-month moving average of shipments into Texas with placements, which we define as the first appearance of each new home in TDHCA records, by installation report or by title, whichever comes first. Placements counts a home once, whether it was sold at retail and titled or placed into a community’s inventory, so it is the broadest signal we have for new homes that are sited.
Placements averaged 1,387 homes a month over the twelve months through July 2026, about 40 below the shipments average for the same window. The placements average slid from about 1,480 at the start of 2025 to a low near 1,360 this spring and has edged up for two months, while shipments have held between about 1,410 and 1,430 all year, so the spread between the two lines, which opened to more than 70 homes a month last summer, has settled back to about 40. Some of the difference in the spread is homes sold into Texas by retailers in Louisiana, Oklahoma and New Mexico, roughly 500 to 900 a year. Those homes shipped to the retailer’s state and were counted as that state’s shipments, but they were placed and titled in Texas.
The shipments line runs through August and placements through July.
Used Homes
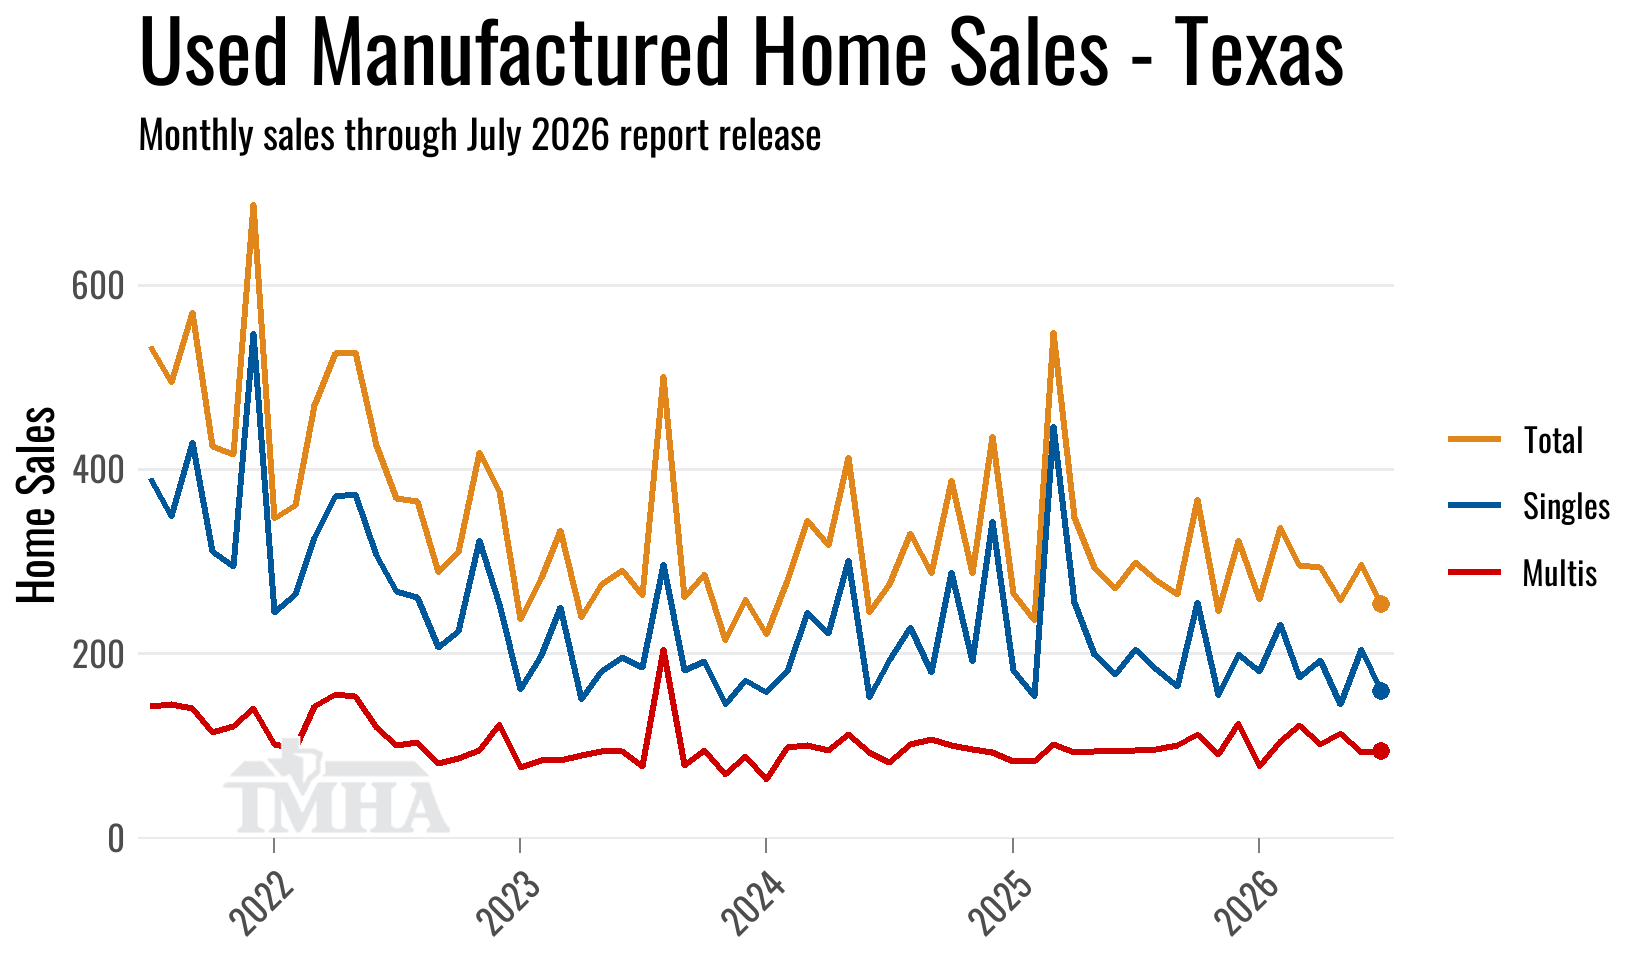
The used home retail sales data is noisy as it includes commercial purchases of park-owned homes after a manufactured home property is sold to a new buyer, but there was a clear downward trend in total transactions in the higher interest rate environment from 2022 through 2024 and have been roughly flat since.
| Used Sales | Singles | Multis | Total |
|---|---|---|---|
| Total for 2026 titled to date: | 1,553 | 871 | 2,424 |
| Change from 2025 (%): | -3.7% | 24.6% | 4.8% |
| Change from 2025 (Units): | -60 | 172 | 112 |
Revised Monthly Totals
Because titles continue to come in for past sales months, here are the prior 12 months and what their current sales totals are at this report release.
| New Sales Month | Singles | Multis | Total | (YoY%) |
|---|---|---|---|---|
| June 2026 | 483 | 855 | 1,338 | 24.3 |
| May 2026 | 510 | 853 | 1,363 | 3.3 |
| April 2026 | 481 | 805 | 1,286 | -8.8 |
| March 2026 | 533 | 805 | 1,338 | -11.0 |
| February 2026 | 427 | 677 | 1,104 | -2.8 |
| January 2026 | 399 | 585 | 984 | -3.8 |
| December 2025 | 523 | 764 | 1,287 | 6.7 |
| November 2025 | 418 | 713 | 1,131 | -13.3 |
| October 2025 | 506 | 815 | 1,321 | -5.6 |
| September 2025 | 522 | 765 | 1,287 | -2.9 |
| August 2025 | 542 | 937 | 1,479 | -1.8 |
| July 2025 | 557 | 781 | 1,338 | 2.4 |
| Used Sales Month | Singles | Multis | Total | (YoY%) |
|---|---|---|---|---|
| June 2026 | 204 | 93 | 297 | 24.3 |
| May 2026 | 145 | 113 | 258 | -2.3 |
| April 2026 | 193 | 101 | 294 | -6.1 |
| March 2026 | 174 | 122 | 296 | -38.5 |
| February 2026 | 232 | 105 | 337 | 51.1 |
| January 2026 | 181 | 78 | 259 | 5.3 |
| December 2025 | 199 | 124 | 323 | -18.8 |
| November 2025 | 155 | 91 | 246 | -8.9 |
| October 2025 | 255 | 112 | 367 | -2.7 |
| September 2025 | 164 | 100 | 264 | -6.0 |
| August 2025 | 183 | 96 | 279 | -13.9 |
| July 2025 | 204 | 95 | 299 | 13.3 |